Home / Commercial
Commercial insuranceBusiness insurance that understands your trade.
For owner-operators with 2 to 50 employees. We know what a general contractor will ask for, what a landlord's lease requires, and what a broker needs before you haul.
Pick your trade. See what matters.
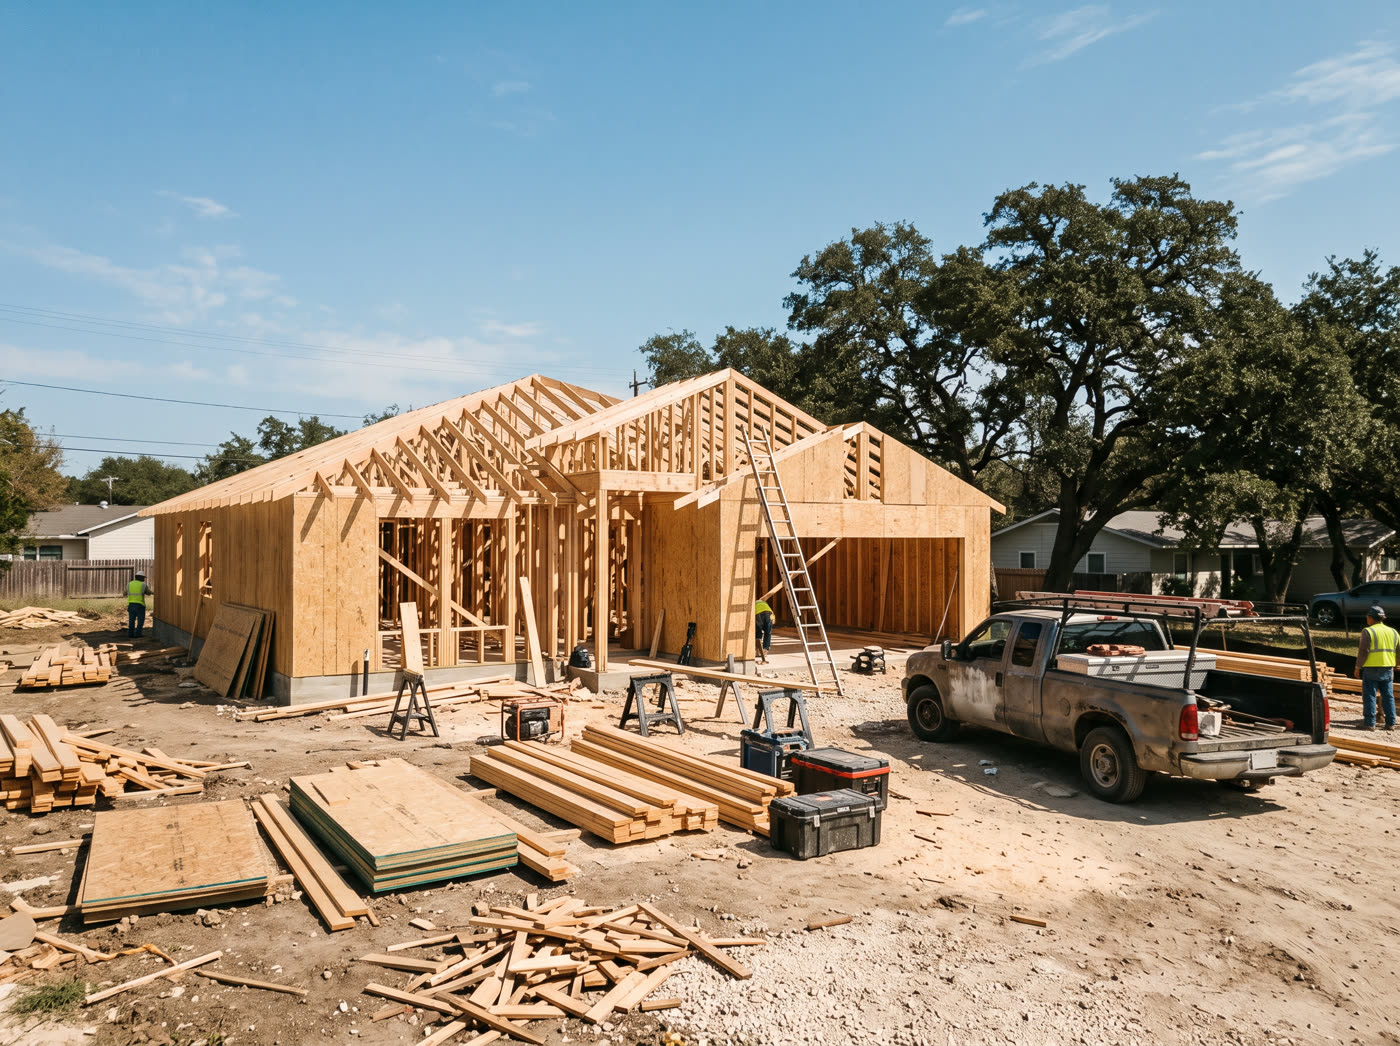
Contractors and trades
Roofers, electricians, plumbers, HVAC, remodelers and general contractors. You need proof of insurance before you start, and coverage that follows the truck.
- General liability, with the additional insured wording your GC asks for
- Tools and equipment (inland marine), on the truck or on the site
- Commercial auto for work trucks and trailers
- Workers' comp or an occupational accident alternative
- Builder's risk for projects under construction
Plain answer: General liability covers injuries and damage you cause to others. It does not cover your own tools. For that you need inland marine coverage.
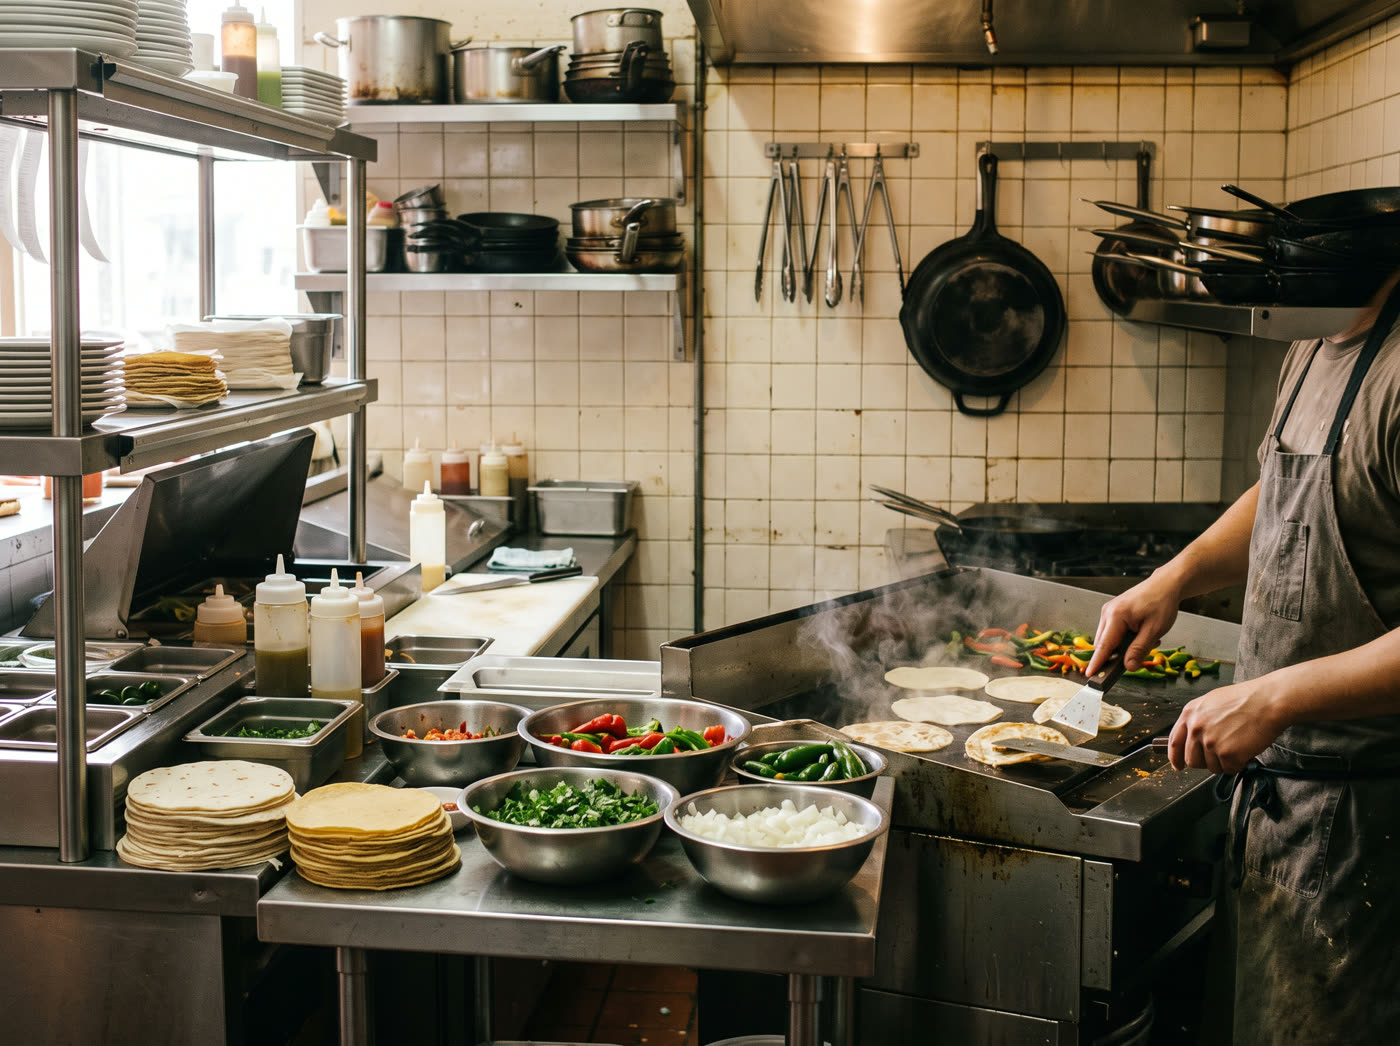
Restaurants, bars and food trucks
Grease fires, slip-and-falls, a walk-in cooler that dies on a Saturday. We build coverage around what actually goes wrong in a kitchen.
- Business owner's policy: property and general liability bundled
- Liquor liability if you serve beer, wine or spirits
- Food spoilage and equipment breakdown
- Business income if a covered loss closes you for a while
- Hired and non-owned auto for delivery runs
Plain answer: Most general liability policies exclude alcohol-related claims. If you serve, liquor liability is a separate line.
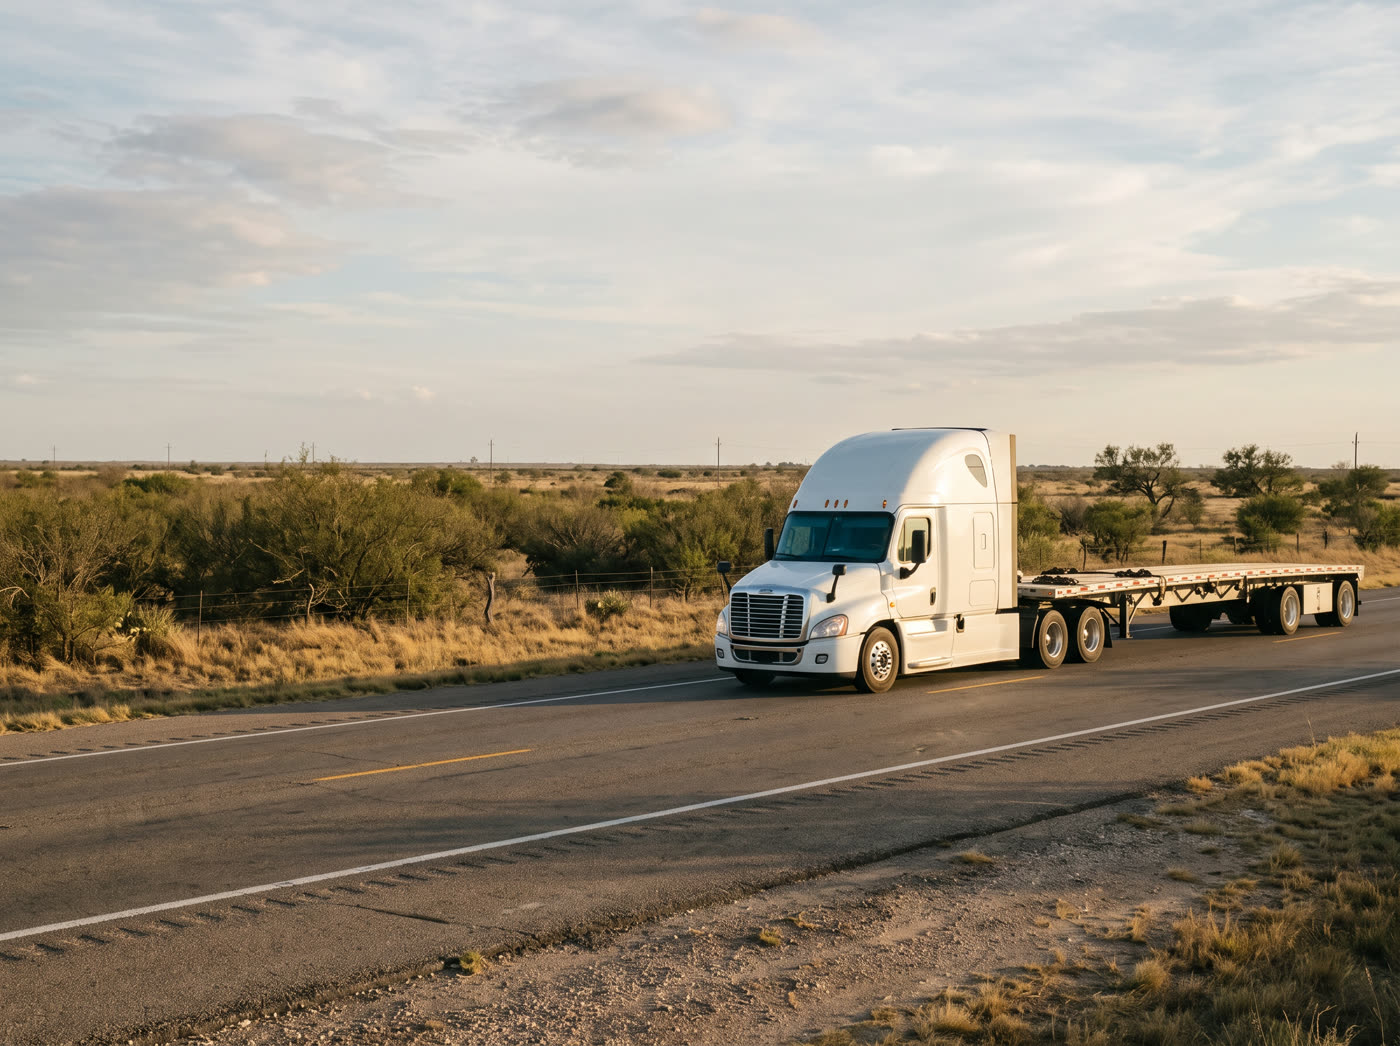
Trucking and hauling
Owner-operators, small fleets and local haulers running I-35, I-10 and Loop 410. We handle the filings so you can keep moving.
- Primary auto liability with federal and Texas filings
- Motor truck cargo for the load you haul
- Physical damage for tractors and trailers
- Non-trucking liability for leased-on drivers
- Occupational accident for 1099 drivers
Plain answer: Three options below. Option 2 is what we would usually pick for a 6-truck operation: same limits as Option 3, lower premium, slightly higher deductible.
Medical and professional offices
Clinics near the Medical Center, dental and therapy practices, CPAs, consultants. Your biggest risks are advice, data and the front door.
- Professional liability (errors and omissions)
- Cyber liability for patient and client data
- Business owner's policy for the office and equipment
- Employment practices liability
Plain answer: Professional liability covers claims that your advice or service caused someone a financial loss. General liability does not.
Retail and showrooms
Boutiques, hardware stores, feed stores and showrooms. Customers walk in, stock sits on shelves, and summer storms knock out power.
- Property for your building, fixtures and inventory
- General liability for customer injuries
- Business income and utility interruption
- Crime coverage for theft and employee dishonesty
Plain answer: Stock values change by season. We set a limit that covers your busiest month, not your slowest.
Startups and service firms
Investors, enterprise clients and landlords will all ask for proof of coverage. We get you the right policies without paying for what you do not need yet.
- Technology errors and omissions
- Cyber liability and data breach response
- Directors and officers (D&O) for funded companies
- General liability and a BOP for the office
Plain answer: D&O covers personal claims against founders and board members for business decisions. Investors usually require it after a priced round.
The policies, in plain words.
| Coverage | What it covers | What it does not |
|---|---|---|
| General liability | Injuries and property damage you cause to other people. | Your own tools, vehicles, employees or professional advice. |
| Commercial auto | Vehicles used for work: liability and damage. | Personal vehicles on a personal policy used for jobs. |
| Workers' comp | Medical bills and lost wages for injured employees. | Independent contractors (usually). Optional in Texas. |
| Commercial property | Building, equipment, stock. Fire, wind, hail, theft. | Flood and earthquake, unless added. |
| Business owner's policy | Property and general liability bundled for small businesses. | Auto, workers' comp, professional liability. |
| Umbrella | Extra liability above your other policies, often in $1M steps. | Anything the underlying policy excludes. |
| Cyber | Data breach costs, ransomware, customer notification. | Hardware replacement, in most forms. |
Straight answers about your coverage, usually the same day.
One call. We compare real options from multiple carriers and explain what each one covers, in plain words.